Sydney, Nova Scotia

Franchise loans &
financing in Sydney

Your ambition. Our financing experience.

We help Sydney entrepreneurs prepare franchise loans for new businesses, acquisitions and expansion, with a business plan that connects local premises decisions to the investment and operating forecast.

Former bankers
& franchisees
Business plans
built in-house
Banks, credit
unions & BDC
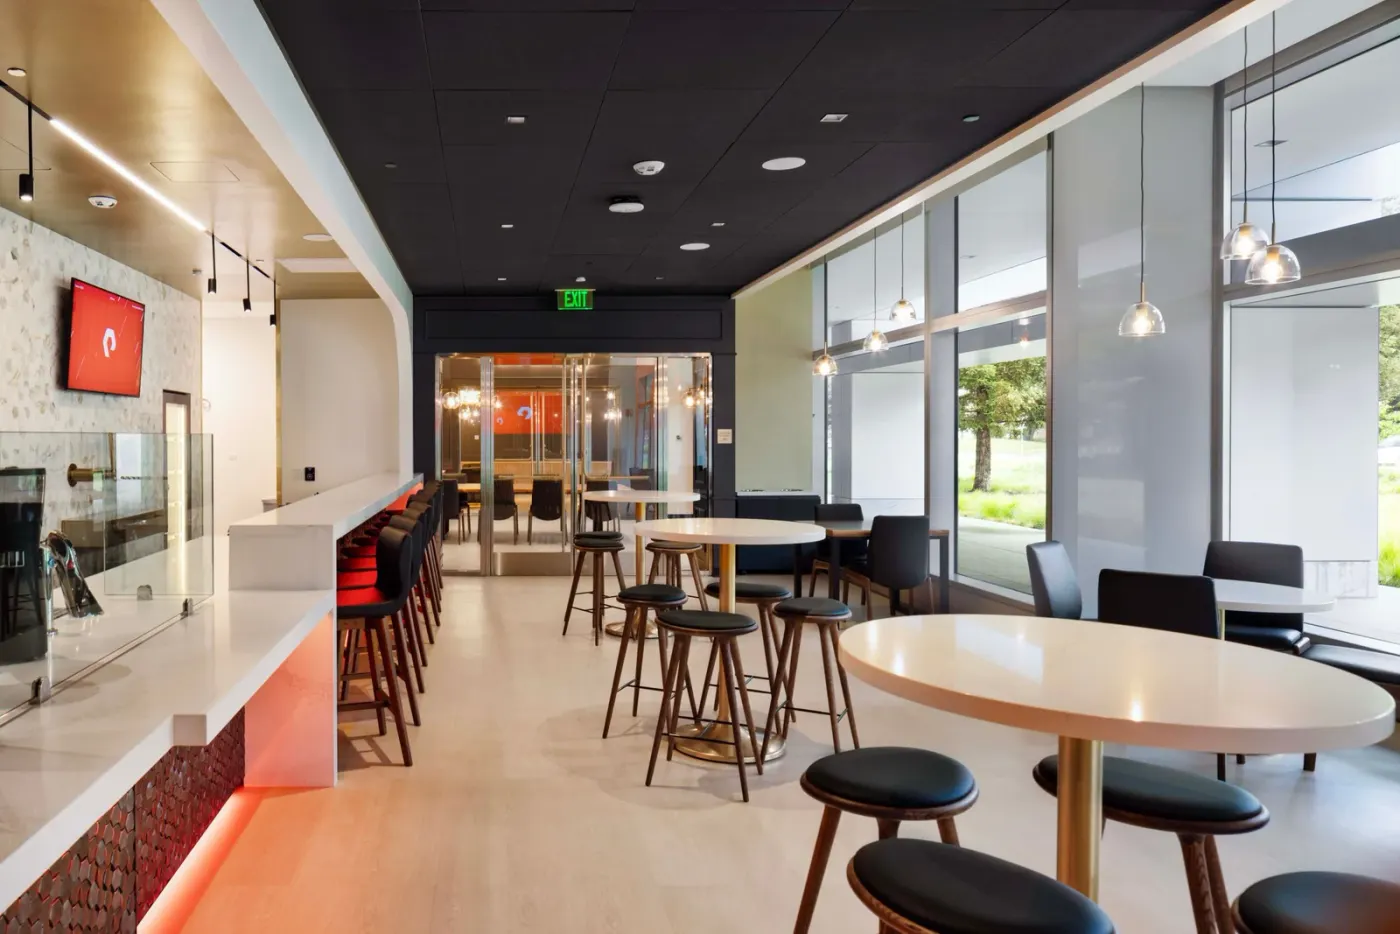
Restaurant interior with customer seating and a service counter
YOUR NEXT FRANCHISE

Big plans start
with the right preparation.

EXPERIENCE ACROSS CANADA

We have arranged franchise financing
for these businesses & more.

A&W
Boston Pizza
Circle K
Dairy Queen
Petro-Canada
Pet Valu
The UPS Store
BarBurrito
Esso
Sunset Grill
Mobile Klinik
INS Market
The Burger’s Priest
Pizzaville
Topper’s Pizza
Thai Express
Mucho Burrito
MR.SUB
Pizza Delight
South St. Burger
Freshii
Pita Pit
Quesada
Noodlebox
Fat Bastard Burrito
Burger King
Subway
Tim Hortons
Second Cup
Booster Juice
COBS Bread
Coffee Culture Café & Eatery
Coffee Time
Jugo Juice
Eggsmart
Global Pet Foods
Great Clips
Massage Addict
Kumon
Mr. Lube + Tires

LOCAL PREPARATION. BANKING EXPERIENCE.

Your Sydney location.
A complete business case.

Sydney is served by Cape Breton Regional Municipality, so CBRM is the relevant municipal starting point for land-use and development questions. Its business guidance recommends checking the proposal before investing. We support Sydney clients remotely from North York, Ontario and use the actual project address, rather than implying a separate Sydney municipal approval or a local Fund My Franchise office.

Local resources checked .

CBRM SITE REVIEW

Confirm the proposal before committing opening funds

CBRM’s starting-a-business guidance directs applicants to its Planning and Development team for zoning and bylaw questions. Provide the proposed Sydney address, business activity and intended alterations. A franchise approved by its brand still needs to fit the premises and local requirements.

Turn the response into a costed project plan. Identify whether the chosen unit needs construction, equipment installation, signs or other work before trading. Put professional advice and supplier quotes behind the major budget items. If the project needs further municipal review, explain the unresolved step and the costs that depend on it instead of describing the opening date as certain.

  • Use CBRM contacts for the Sydney property and proposed use.
  • Separate confirmed work from allowances awaiting review or quotations.
  • Coordinate deposits and construction commitments with outstanding conditions.

YEAR-ROUND CASH FLOW

Distinguish recurring customers from occasional demand

A Sydney franchise forecast should identify who will buy from the particular location. If your concept expects visitor, event or seasonal business, show that as a supported assumption and distinguish it from recurring local demand. Do not treat a busy launch period as evidence that every month will perform the same way.

For a resale, ask for monthly sales and expense records where available so the operating pattern can be understood. For a startup, build a reasoned monthly forecast and test a more cautious case. We help show how wages, occupancy costs, royalties and stock purchases will be funded through the year, and how much cash should remain after the initial investment.

  • Identify the customer segments and evidence behind expected sales.
  • Explain changing hours or staffing rather than averaging the entire year.
  • Keep working capital separate from equipment and premises spending.

MATCH THE LOAN TO THE PROJECT

How to approach franchise financing in Sydney

Start with the amount and timing of your project costs, the investment you can contribute and a cash-flow forecast. We prepare the financing request and in-house business plan, then coordinate with suitable banks, credit unions or BDC. Your location, transaction and lender criteria help determine the options.

New franchise loans

Bring equipment and renovation estimates together with deposits, training, inventory and opening cash. Identify which costs are confirmed and which are still estimates.

Plan a new opening

Franchise purchases

A resale needs the seller’s financial records, purchase structure, lease and any required upgrades. A going concern and a new build call for different evidence.

Prepare an acquisition

CSBFL & lender eligibility

Program eligibility and a lender’s credit approval are separate assessments. Review eligible costs and required documents before assuming a particular loan will cover the project.

Understand CSBFL requirements

Fund My Franchise helps arrange the application; the lender decides approval, security, rates and repayment terms. Ask about fees and conditions before accepting an offer.
GET YOUR APPLICATION MOVING

What to prepare for a franchise loan in Sydney

Start with the information you have. We will help identify the missing pieces before approaching a lender.

  • The franchise brand, proposed Sydney address and opening or purchase timetable.
  • A project budget, available owner investment and summary of your experience.
  • The proposed lease, equipment quotes and contractor estimates.
  • The franchisor’s documents, fee schedule and operating requirements.
  • For a resale, seller financials, purchase terms and required refurbishment costs.
Apply for Financing

Confirm commitments and financing conditions with your independent legal and financial advisers before signing.

YOUR QUESTIONS, ANSWERED

Planning a franchise
in Sydney?

A few answers before
we get started.

Who handles municipal questions for a Sydney franchise?

Start with Cape Breton Regional Municipality’s Planning and Development team. CBRM’s business guidance covers Sydney and directs applicants to the relevant land-use and permit information. Provide the exact address and proposed activity so the response relates to your project.

Should visitor demand be included in a Sydney financing forecast?

Include it when your own research supports it, with the relevant months and costs clearly identified. Keep a separate view of recurring demand and test lower visitor-related sales. A financing application is stronger when it explains variability than when it assumes the same revenue every month.

Can a Sydney resale application rely on annual financial statements alone?

Annual statements are useful, but monthly trading information can reveal cash-flow patterns that annual totals hide. Add lease terms, equipment details, franchise transfer requirements and any planned changes. We help organize those items into a forecast for your ownership and proposed financing.

LET’S BUILD YOUR NEXT CHAPTER

Your Sydney franchise.
Let’s plan the financing.

Tell us about the brand, the location and where you are in the process.

START YOUR APPLICATION

Apply for franchise
financing in Canada

Tell us which franchise you are considering, where it will operate and the financing you need. Our team will follow up to discuss lender options, your business plan and the next steps.

Prefer to speak with us?

647-777-9205info@fundmyfranchise.ca
Reviewing business plans and financial projections

This is an initial financing inquiry. Completing it does not run a credit check or commit you to a loan.

Apply for Financing

Tell us about your franchise and funding needs.

Your information is used to respond to your inquiry.